Accrued Advertising Expenses: How to Record and Calculate Them
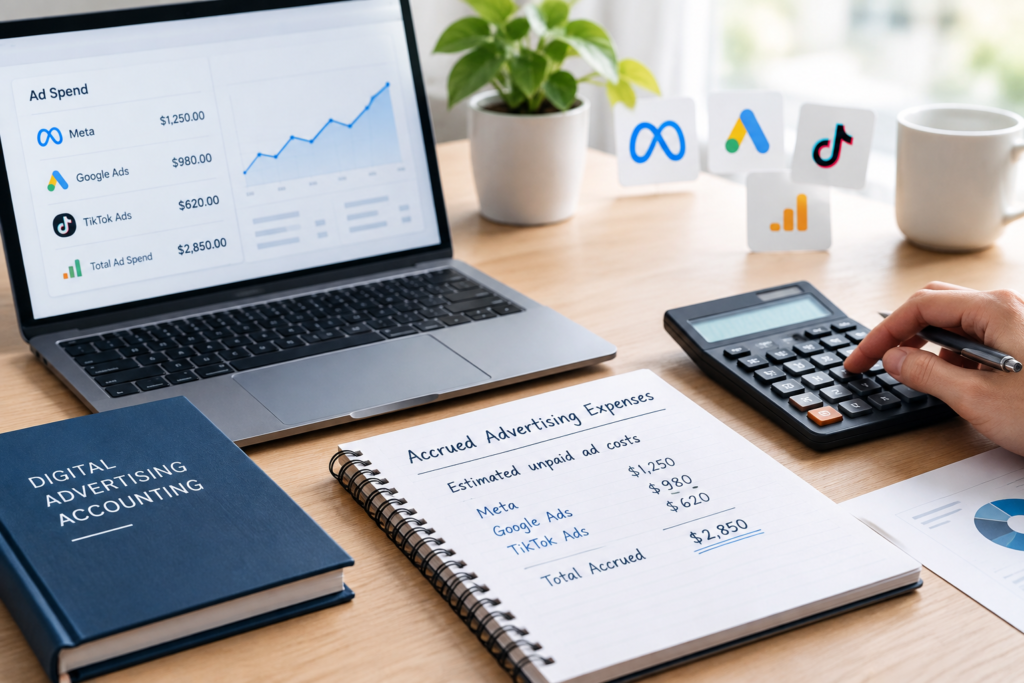
If you run ads for an e-commerce store, you already know the annoying truth about ad platform billing: the money leaves your account on a schedule that has nothing to do with your accounting calendar. Meta typically bills every 30 days or once you cross a spend threshold. Google Ads can bill daily, weekly, or monthly depending on how the account is configured. TikTok and Amazon Ads each run their own cycle too. None of them care that your month ends on the 30th. That mismatch is exactly why accrued advertising expenses exist as a line item. Without one, your books understate what the business actually spent to acquire customers that month, and your numbers quietly drift out of sync with reality. What Is an Accrued Advertising Expense, and How Is It Different From Accounts Payable? An accrued advertising expense is advertising cost your business has incurred but hasn’t yet been billed for. You know the spend happened because you can see it live on the platform dashboard. You just don’t have an invoice yet, which means there’s nothing to enter as a normal bill. Is accrued advertising expense a liability? Yes. It’s classified as a current liability on the balance sheet, sitting alongside accounts payable, accrued payroll, and other short-term obligations. The distinction people mix up most is accrued advertising versus accounts payable, and it’s worth being precise about it: Once the invoice lands, the accrual gets reversed and the real amount moves into accounts payable until it’s paid. They’re not interchangeable categories; they’re two stages of the same expense moving through your books. This all sits under the broader concept of accrual accounting, which recognizes expenses when they’re incurred rather than when cash actually leaves the bank, a concept known as the matching principle. Here, we’re staying narrow and practical: how advertising accrual accounting actually plays out for e-commerce sellers running paid ads across multiple channels. Why Ecommerce Sellers Need to Accrue Unbilled Ad Spend A service business with a flat monthly ad retainer barely needs to think about this. An e-commerce store running dynamic Meta and Google campaigns is a different animal. Spend fluctuates daily based on performance, promotions, and inventory pushes, and different platforms invoice on different clocks. A brand spending $40,000 a month across three channels can easily have $8,000 to $12,000 sitting unbilled at any given moment, spread across billing cycles that don’t line up with each other or with your close date. If that unbilled chunk never hits your books, your income statement understates expenses in the month the spending actually happened, then overstates them the following month once the invoice finally lands. Repeat that pattern for a year, and your monthly margin numbers stop reflecting reality, which matters if you’re using them to guide inventory, hiring, or ad budget decisions, or if you’re heading into a valuation event where a buyer’s diligence team is likely to flag inconsistent expense timing as a red flag. Accrued Advertising Expense Journal Entry: How to Record It Here’s the standard adjusting journal entry at month end, before the invoice arrives: Example: your Meta Ads dashboard shows $6,200 in spend that hasn’t been billed yet as of month end. Account Debit Credit Advertising Expense $6,200 Accrued Advertising Payable $6,200 The following month, once the real invoice arrives, you reverse the accrual and record the confirmed liability: Some businesses automate this with a standing reversing entry that flips automatically on the first day of the next period rather than reversing it manually once the invoice shows up. Either approach works; what matters is that the estimate doesn’t stay on the books alongside the real invoice, which is where double counting creeps in. If your estimate was close, the reversal nets out cleanly. If it wasn’t, book a small true-up entry to Advertising Expense for the difference: debit if you underestimated, credit if you overestimated. How to Estimate Your Advertising Accrual Each Month This is the part most explainers skip, and it’s the part that actually matters day to day. You’re not guessing blind. Every ad platform gives you a live spend dashboard, and estimating accrued advertising costs is really just a matter of pulling the right numbers before you close the books: Quick example: Meta shows $4,100 unbilled, Google shows $2,900 unbilled, and your agency’s management fee, billed the following month based on total spend, is estimated at $700. Your total accrual for the month is $7,700. Where Accrued Advertising Costs Appear on Your Financial Statements Statement Where it shows What it represents Income Statement Advertising Expense (operating expenses) The full cost incurred during the period, accrued and invoiced combined Balance Sheet Accrued Liabilities (current liabilities) The unpaid, unbilled portion still owed as of the reporting date The expense hits the income statement in the month it was actually incurred, regardless of when the invoice arrives. The liability stays on the balance sheet until it’s either paid or replaced by a confirmed accounts payable entry. Common Mistakes in Advertising Expense Accounting Underaccruing because only one channel gets checked. A store running Meta and Google will sometimes accrue the Meta number and forget Google entirely, usually because Google’s billing feels less visible on a day-to-day basis. Forgetting to reverse the entry. If last month’s accrual never gets reversed once the real invoice comes in, you end up double counting the expense. This is one of the most common and most expensive errors in advertising accrual accounting, and it quietly inflates expenses month after month until someone finally reconciles the account. Treating agency fees and platform spend as one lump sum. They’re often billed on different schedules by different parties, so they sometimes need separate accrual lines instead of one blended guess. Applying this under cash basis accounting. If your business keeps books on a cash basis, you generally don’t need this entry at all, since a cash basis recognizes expenses when paid, not when incurred. This trips up a fair number of smaller sellers who apply accrual advice