If your idea of month-end close is “reconcile the bank account and move on,” you’re doing about one step out of eighteen. A real close includes the full set of reconciliations, accruals, and reviews that turn a month of scattered transactions into financial statements you can trust and act on. For e-commerce sellers, that process looks meaningfully different from a standard small business close.
Two things make it different. First, payout timing rarely lines up with when a sale actually happens. Second, inventory can exist in three places at once, on your shelf, in transit, and at a third-party warehouse, and all three need to agree with what your books say you own. Miss either one and your books can still balance perfectly while telling you the wrong story about how the business is actually doing.
This month-end close checklist is built around that reality. For the broader day-to-day bookkeeping process, see our e-commerce bookkeeping checklist. It’s a working version of the process we use with e-commerce clients, laid out here so you can run it yourself or hand it to a bookkeeper as a repeatable SOP.
Why Ecommerce Businesses Need a Different Month-End Close
Under accrual accounting, revenue is recognized when it’s earned, generally when an order ships or a performance obligation is otherwise satisfied, not when the cash actually lands in your account. That distinction matters more for e-commerce sellers than most, because marketplaces and payment processors don’t pay out on the same schedule sales happen. Amazon, Shopify Payments, and similar processors typically hold funds for a period and disburse on their own rolling schedule, often net of fees, refunds, and any reserve they’re holding back. If your books only recognize revenue once a payout hits the bank, you’re effectively running on a cash basis without deciding to, and month-to-month comparisons stop being reliable because they’re really just tracking when money arrived rather than when it was earned.
Inventory adds a second layer of complexity. Units on the shelf, units in transit from a manufacturer, and units sitting at a 3PL all need to reconcile against your accounting system’s inventory balance. A mismatch here does more than distort the balance sheet, it flows directly into cost of goods sold and can shift your margins in a direction you won’t notice until the gap has grown.
Neither issue means close needs to be complicated. It means the checklist needs to include the right controls, not simply more of them.
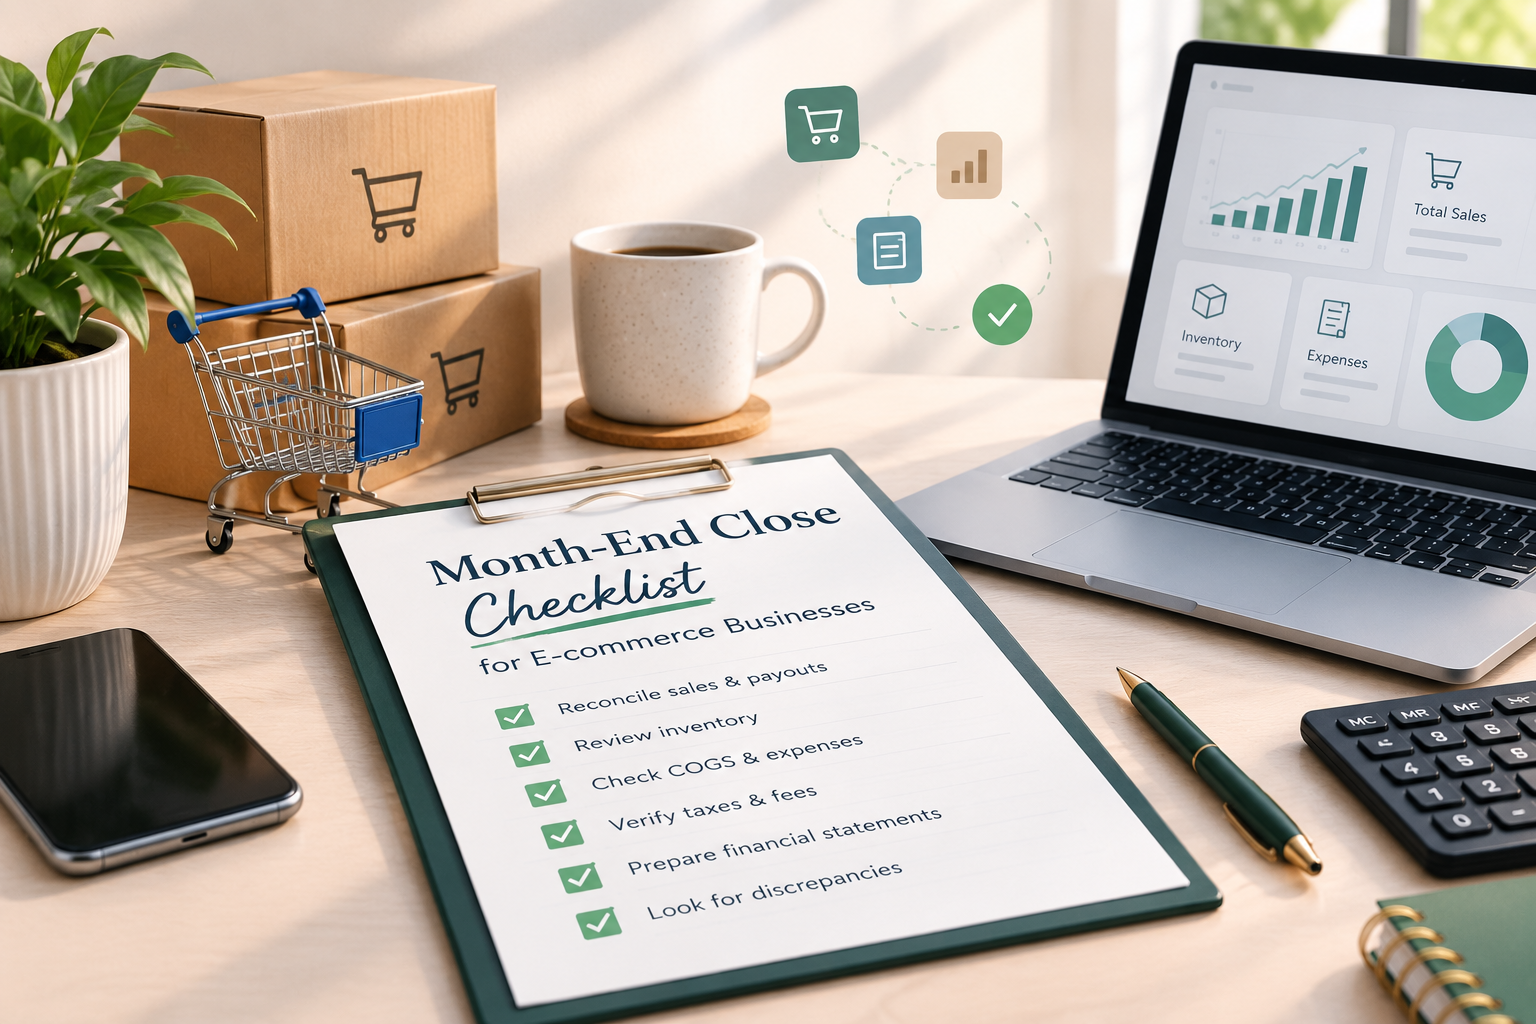
18-Step Month-End Close Checklist for E-commerce Businesses
1. Set and communicate a cutoff date. Choose the exact date and time transactions stop counting for the month, and pull data from every channel, Shopify, Amazon, Walmart, and your payment processor, as of that same cutoff. Mismatched cutoffs across platforms are a common reason a close doesn’t tie out cleanly.
2. Reconcile every bank account. Match each transaction in your books against the corresponding bank statement for every operating, savings, or reserve account.
3. Reconcile credit card statements. Business credit cards get overlooked more often than bank accounts. Every charge should be categorized and matched, and any personal charges on a business card should be flagged rather than left sitting in a suspense account.
4. Reconcile marketplace and payment processor payouts. Match each payout deposit against the underlying sales, fees, refunds, and reserve holdbacks shown in the platform’s payout report, not just the total that hit your bank. This is where a large share of e-commerce close errors originate.
5. Record accrued revenue for sales not yet paid out. If an order was fulfilled during the month but the related payout arrives afterward, that revenue is generally recognized in the month it was earned under accrual accounting, with a corresponding receivable until cash is received. Skipping this step is a common reason e-commerce income statements look choppy from one month to the next.
6. Reconcile inventory quantities across all locations. Compare your inventory management system against a physical or cycle count, including stock at a 3PL and inventory in transit. Investigate variances before adjusting them away.
7. Update cost of goods sold. Once inventory is confirmed, make sure COGS reflects units actually sold during the month, valued under your chosen costing method (FIFO, LIFO, or weighted average), and includes landed costs like freight and duty rather than just the base vendor invoice price.
8. Review and adjust inventory reserves. If any inventory is slow-moving, damaged, or unlikely to sell at full price, check whether your obsolescence or shrinkage reserve still reflects current reality.
9. Record depreciation and amortization. Book the month’s depreciation on equipment, warehouse fixtures, or vehicles, and amortization on any capitalized software or intangible assets.
10. Accrue expenses incurred but not yet billed. This typically includes ad spend that ran but hasn’t been invoiced, contractor work completed but not yet paid, and freight or carrier charges that lag by a few weeks. These are recognized in the period incurred, regardless of when they’re actually paid.
11. Reconcile accounts payable. Confirm outstanding vendor bills match what suppliers show as owed, and check for anything double entered or missed entirely.
12. Reconcile accounts receivable. For sellers with wholesale, B2B, or net terms activity, confirm the aging schedule reflects what’s genuinely outstanding and flag anything moving into a higher-risk category.
13. Reconcile sales tax collected against sales tax remitted. This step is skipped more often than it should be. A small gap here compounds every month; it goes unchecked and can become a meaningful liability by year-end.
14. Review deferred revenue, if applicable. If you sell gift cards, subscriptions, or anything paid for in advance of delivery, confirm the deferred revenue balance still matches what hasn’t yet been fulfilled.
15. Review the returns and chargeback reserve. Estimate expected returns and chargebacks based on recent trends, and confirm the reserve on your books is reasonably close to that estimate rather than left at whatever number it was months ago.
16. Review payroll and contractor accruals. Confirm wages, payroll taxes, and contractor payments earned during the month but paid after month-end are accrued in the correct period.
17. Review the trial balance for anomalies. Look for negative balances in accounts that shouldn’t run negative, round numbers that look more like placeholders than real entries, and accounts that normally move but show no activity this month.
18. Generate and review the financial statements. Pull the balance sheet, income statement, and cash flow statement, and read them line by line. Compare against last month and, if you have the history, the same month last year. Anything that moved sharply without a clear cause deserves an explanation before you lock the period.
How Long Should a Month-End Close Take?
For a business with reasonably current bookkeeping throughout the month, a full close often takes somewhere in the range of three to seven business days after month end. Businesses running multiple channels, a 3PL, and wholesale activity alongside direct-to-consumer sales tend to land closer to seven to ten days, particularly while the process is still new. If close consistently stretches beyond two weeks, that’s often a sign bookkeeping fell behind during the month itself, and close is quietly absorbing cleanup work it was never meant to do.
Soft Close vs. Hard Close: Which Does Your Business Need?
Not every month needs the same level of rigor. A soft close is a faster pass, accurate enough to support internal decisions about cash and margin, but not necessarily built to withstand outside scrutiny. A hard close works through the full checklist above to a standard that would hold up under review by a lender, investor, or accountant. Many e-commerce businesses run a soft close most months and reserve a hard close for quarter-end, especially in earlier stages when the added rigor of a monthly hard close may not yet be worth the time it takes.
Who Should Handle the Month-End Close?
In many small e-commerce operations, the founder handles close alone in the first year or two, and that can work fine as long as the checklist is actually followed rather than skipped during busy periods. As transaction volume grows, the reconciliation work usually moves to a bookkeeper, with a controller or fractional controller reviewing the output, investigating anomalies, and connecting the close back to the broader financial picture. If close is consistently late, consistently off, or something you find yourself avoiding, that’s often the point where bringing in outside help starts paying for itself.
7 Common Month-End Close Mistakes to Avoid
Recording revenue based on when cash was deposited rather than when the sale was earned is one of the more frequent issues, since it quietly shifts income between periods. Treating inventory counts as optional, doing them only annually instead of monthly or by cycle count, is another, since small discrepancies compound rather than stay flat. A third is locking the books before all vendor bills for the month have been entered, which understates expenses and can overstate profit right when that number is being used to make a real decision.
Build a Faster, More Reliable Month-End Close
A month-end close checklist isn’t about adding bureaucracy to a small business; it’s about making sure the numbers you’re using to make decisions actually reflect what happened. For e-commerce sellers specifically, that means paying close attention to payout timing and inventory accuracy, the two areas where a generic checklist tends to fall short.
Run through these eighteen steps consistently, and your financial statements become something you can trust, plan around, and hand to a lender, investor, or accountant without a second thought. If you need help keeping your e-commerce books accurate and your month-end close on track, get in touch with our team to discuss how we can help.